What Is a Home Appraisal? A Clear Guide to Understanding Home Appraisals
A home appraisal is a professional evaluation of a property's market value conducted by a licensed appraiser. It determines how much a home is worth based on various factors, including location, condition, and comparable sales. This assessment helps buyers, sellers, and lenders make informed decisions during real estate transactions.
Understanding a home appraisal matters because it influences loan approvals, sale prices, and refinancing options. Lenders rely on these valuations to minimize risk and ensure the property's value justifies the loan amount. For homeowners, an appraisal provides insight into current market conditions and potential equity.
This article will cover the home appraisal process, key factors influencing value, how appraisals impact buyers and sellers, and tips for preparing your property. Additionally, we’ll compare different appraisal types and explain related terminology to give you a full picture of what to expect.
How Does the Home Appraisal Process Work?
The Role of the Licensed Appraiser
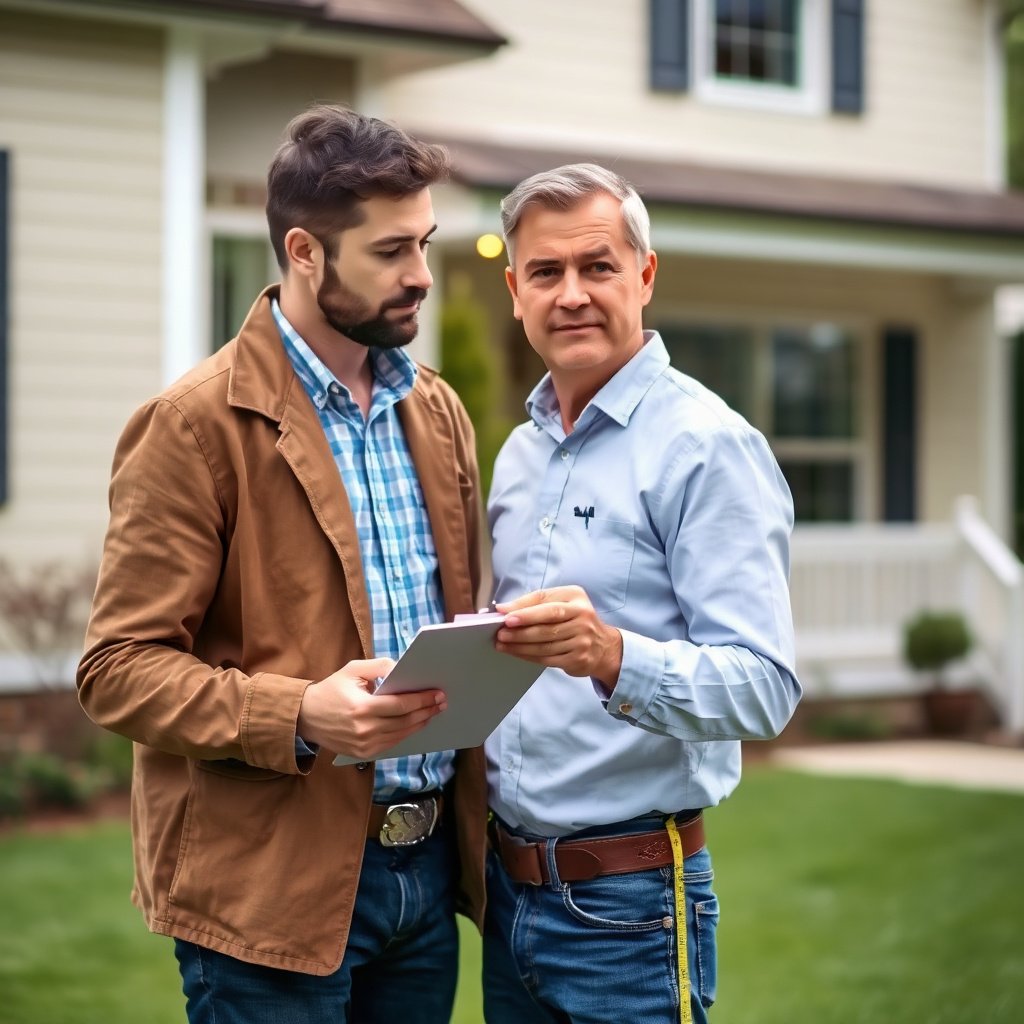
Licensed appraisers are trained professionals certified to assess residential property values. They visit the home, inspect its features, and analyze data to produce an unbiased report. Their expertise ensures the appraisal reflects fair market value based on current conditions.
Appraisers must adhere to strict standards set by regulatory bodies to guarantee accuracy and impartiality. They typically work independently or through appraisal companies, without direct financial interest in the transaction.
Steps in Conducting a Home Appraisal
The appraisal begins with a visual inspection where the appraiser measures the home’s size, notes the condition, and records details like the number of bedrooms and upgrades. They consider external factors like neighborhood quality and proximity to schools.
Next, the appraiser researches recent sales of comparable homes, known as 'comps,' to benchmark value. This comparative analysis combined with adjustments for differences leads to the final appraisal report provided to lenders or clients.
- Property inspection
- Comparative market analysis
- Final valuation report
Key Factors Influencing Home Appraisal Value

Property Condition and Features
The condition of the home greatly impacts its appraised value. Renovations, updated systems, and well-maintained structures increase worth, while visible damage or outdated elements can reduce it. Interior features, such as kitchen quality and energy-efficient upgrades, also matter.
Appraisers pay close attention to functional spaces, usable square footage, and any additions that affect livability. Cleanliness and curb appeal during inspection can influence subjective assessments within reason.
Neighborhood and Market Conditions
The local real estate market and neighborhood characteristics play essential roles. Nearby amenities, school district ratings, crime levels, and overall demand influence value. Economic trends like rising or falling sales prices impact the appraisal’s referencing of comparable sales.
Appraisers adjust for factors such as lot size, view quality, and community developments. Appreciation trends or recent sales volume within the vicinity also shape the final valuation, reflecting what buyers are currently willing to pay.
Why Home Appraisals Matter for Buyers and Sellers
Protecting Buyers’ Financial Interests
For buyers, appraisals ensure they do not overpay for a property. Lenders require appraisals to confirm the home’s value matches the loan amount, lowering risk of loan default. If an appraisal comes in low, buyers may renegotiate price or adjust financing options.
An accurate appraisal gives buyers confidence about the investment they are making and serves as a safeguard against inflated pricing or undisclosed issues affecting worth.
For more on this, see our related guide: How to Finance a Lakefront Home: Essential Tips and Loan Options.
Helping Sellers Set Realistic Prices
Sellers benefit from appraisals by understanding their home’s market value, which guides listing price decisions. Overpricing can result in longer time on market, while underpricing risks leaving money on the table.
An appraisal also provides evidence during negotiations if buyers question the asking price and supports smoother closing processes when aligned with lender assessments.
Types of Home Appraisals and When to Use Them
Traditional Full Appraisal
A traditional full appraisal is the most comprehensive method, including a physical inspection and detailed market analysis. It is typically required for mortgage financing, refinancing, and legal purposes.
This appraisal type provides the most accurate valuation because it considers all relevant factors and is prepared by licensed, certified appraisers following strict standards.
Alternative Appraisal Methods
There are quicker, less expensive appraisal options such as drive-by appraisals and desktop appraisals. Drive-by appraisals involve external home inspection without entry, while desktop appraisals rely mainly on data and comps without physical visits.
These types are commonly used when speed is needed or for lower-risk refinances but might be less precise and not accepted by all lenders.
- Drive-by appraisal
- Desktop appraisal
- Broker price opinions (BPOs)
Preparing Your Home for an Effective Appraisal
Presentation and Maintenance Tips
Preparing your home neatly can positively influence an appraiser’s impression. Clean and declutter spaces, make minor repairs, and improve curb appeal by maintaining landscaping or painting exterior surfaces.
Documenting any improvements or recent upgrades with receipts or permits allows the appraiser to consider their contribution to value. Good presentation doesn’t inflate value but supports accurate assessment.
- Clean and declutter
- Fix visible issues
- Enhance curb appeal
For more on this, see our related guide: How to Sell a Vacation Home: A Step-by-Step Guide for Maximum Profit.
Providing Relevant Information to the Appraiser
Offering the appraiser access to relevant documents such as previous appraisal reports, listings of comparable properties, or details about recent renovations can help create a more accurate valuation.
Being available for questions during inspection and communicating honestly about your property’s features helps address any uncertainties promptly.
Common Challenges and Misconceptions About Home Appraisals
Why Appraisal Values Sometimes Differ from Sale Prices
It’s common for appraisal values to differ from agreed sale prices due to market fluctuations, buyer-seller negotiations, or unique property features that don’t align with comps. Appraisals base value on objective data and recent sales, which might lag behind current market demand.
Understanding that appraisals are snapshots in time helps set realistic expectations when discrepancies arise. Negotiations often balance these differences.
For additional background on home appraisals and their methodology, you can visit this detailed resource. Home appraisal information at Wikipedia.
How to Handle a Low Appraisal
A low appraisal can disrupt financing or sale terms, but options include challenging the appraisal with additional comps or evidence, requesting a second appraisal, or renegotiating price with the seller.
Buyers and sellers benefit from remaining flexible and consulting real estate professionals when low appraisals occur to find workable solutions.
Types of Home Appraisals Compared
Here’s a comparison of common appraisal types to clarify their uses, accuracy, and costs.
| Appraisal Type | Inspection Level | Typical Cost | Use Cases | Turnaround Time |
|---|---|---|---|---|
| Traditional Full Appraisal | Full interior and exterior inspection | $300-$500 | Mortgage, refinancing, legal | 3-7 days |
| Drive-by Appraisal | Exterior inspection only | $150-$300 | Quick refinances, low-risk loans | 1-3 days |
| Desktop Appraisal | Data and comps only, no inspection | $75-$150 | Streamlined refinances, portfolio reviews | 1-2 days |
| Broker Price Opinion (BPO) | Brief exterior or no inspection | $50-$100 | Pre-listing estimates, internal use | 1-2 days |
Frequently Asked Questions
How long does a home appraisal take?
The physical inspection usually takes about 30 to 60 minutes, but the full report typically takes 3 to 7 days to complete depending on workload and appraisal type.
Who pays for the home appraisal?
Typically, the buyer arranges and pays for the appraisal as part of the mortgage process, though payment responsibility can vary depending on local practices.
Can I challenge a home appraisal if I disagree with it?
Yes, you can request a reconsideration by providing additional comps or evidence, or in some cases, order a second appraisal to dispute the value.
Does a home appraisal guarantee the sale price?
No, an appraisal estimates market value but sale price is subject to buyer and seller negotiation and may differ due to unique circumstances.
Are appraisals required for all home sales?
Appraisals are generally required by lenders for financed purchases but are not mandatory for cash sales unless specified by parties.
Key Takeaways
- Home appraisals determine a property’s market value through professional evaluation.
- Licensed appraisers use property inspection and comparable sales data to set values.
- Appraisals protect buyers and lenders by confirming fair market prices.
- Different appraisal types vary in accuracy, cost, and speed.
Conclusion
When considering real estate transactions, understanding what a home appraisal entails is vital. It offers an independent valuation of the property based on objective factors like condition and neighborhood trends, helping to clarify fair market price. Approaching this process informed allows buyers, sellers, and lenders to navigate negotiations confidently, avoiding surprises about property worth.
Specific appraisal types fit different needs—from traditional full appraisals that support mortgage lending with thorough inspections, to desktop or drive-by options suited for quicker, less formal valuations. Selecting the appropriate appraisal depends on your transaction type, the property’s complexity, and urgency. Knowing the home appraisal’s role helps identify the best match for your situation and goals.
To move forward, consider scheduling a home appraisal with a licensed, experienced appraiser for the most reliable assessment. Preparing your home and furnishing pertinent information can help achieve a fair and accurate report. Whether buying, selling, or refinancing, a clear grasp of home appraisal fundamentals supports sound real estate decisions.