How to Get a Mortgage for a Second Home: A Complete Guide
Getting a mortgage for a second home requires meeting specific lender criteria distinct from those for a primary residence. To secure financing, you'll need a solid credit score, a low debt-to-income ratio, and enough income to cover both your current mortgage and the new one. Lenders often require a larger down payment—typically 10-20%—for second homes compared to primary residences.
Understanding the differences in qualifying for a second home mortgage matters because lenders consider these properties higher risk. Second homes are usually not your primary source of shelter and may have different resale or rental potentials, influencing the loan terms and interest rates offered. Preparing for additional financial responsibilities and documentation upfront can streamline the approval process.
This article will cover essential factors for getting a mortgage on a second home, including lender expectations, down payment guidelines, credit requirements, and how property type affects loan approval. We’ll also explore how to navigate the application process, compare different mortgage types suitable for second homes, and clarify how tax implications work for these properties.
Understanding Lender Requirements for a Second Home Mortgage
Credit Score and Debt-to-Income Ratio
Lenders look for a strong credit score when approving a second home mortgage, usually 700 or higher. This indicates responsible credit use and lowers the risk for the lender. Additionally, your debt-to-income (DTI) ratio must reflect your ability to handle existing debts plus the new mortgage payment without strain.
A typical maximum DTI is about 43%, though stricter standards can apply. Lower DTI ratios increase your chances of approval and may secure better interest rates. It’s wise to review your credit report and pay down debts before applying.
- Minimum credit score: usually 700+
- Max debt-to-income ratio: typically around 43%
- Lower DTI improves approval odds
Income Verification and Reserves
Lenders require proof of stable income to confirm you can afford both your primary mortgage and the new one on the second home. Pay stubs, tax returns, and employment verification are common documents requested.
Financial reserves—savings that cover several months of mortgage payments—are often required. These reserves give lenders confidence that you can manage unexpected expenses or income interruptions related to your second home.
- Provide pay stubs, tax returns, and employment letters
- Keep 2-6 months of mortgage payments in reserves
Down Payment and Loan Options for Your Second Home
Typical Down Payment Requirements
Second homes usually require a larger down payment compared to primary residences. Expect to put down at least 10% to 20% depending on the lender and loan type. This bigger upfront investment helps offset lender risk due to the secondary nature of the property.
Some conventional loans offer as low as 10% down for second homes, but putting 20% or more can improve your loan terms and reduce private mortgage insurance (PMI) costs.
- Minimum down payment often 10-20%
- Higher down payments can lower interest rates
- Larger down payments reduce PMI requirements
For more on this, see our related guide: Do You Pay Property Tax on a Vacation Home? What You Need to Know.
Mortgage Loan Types Suitable for Second Homes
Conventional loans are the most common choice for second home mortgages, offering competitive rates for creditworthy borrowers. Jumbo loans may be necessary if the property price exceeds conforming loan limits.
FHA loans do not allow financing for second homes, but VA loans may apply in rare cases if you’re eligible and meet occupancy rules. Adjustable-rate mortgages (ARMs) can be an option for short-term ownership plans.
- Conventional loans are standard for second homes
- Jumbo loans for expensive properties
- VA loans have specific occupancy requirements
Types of Properties Considered Second Homes
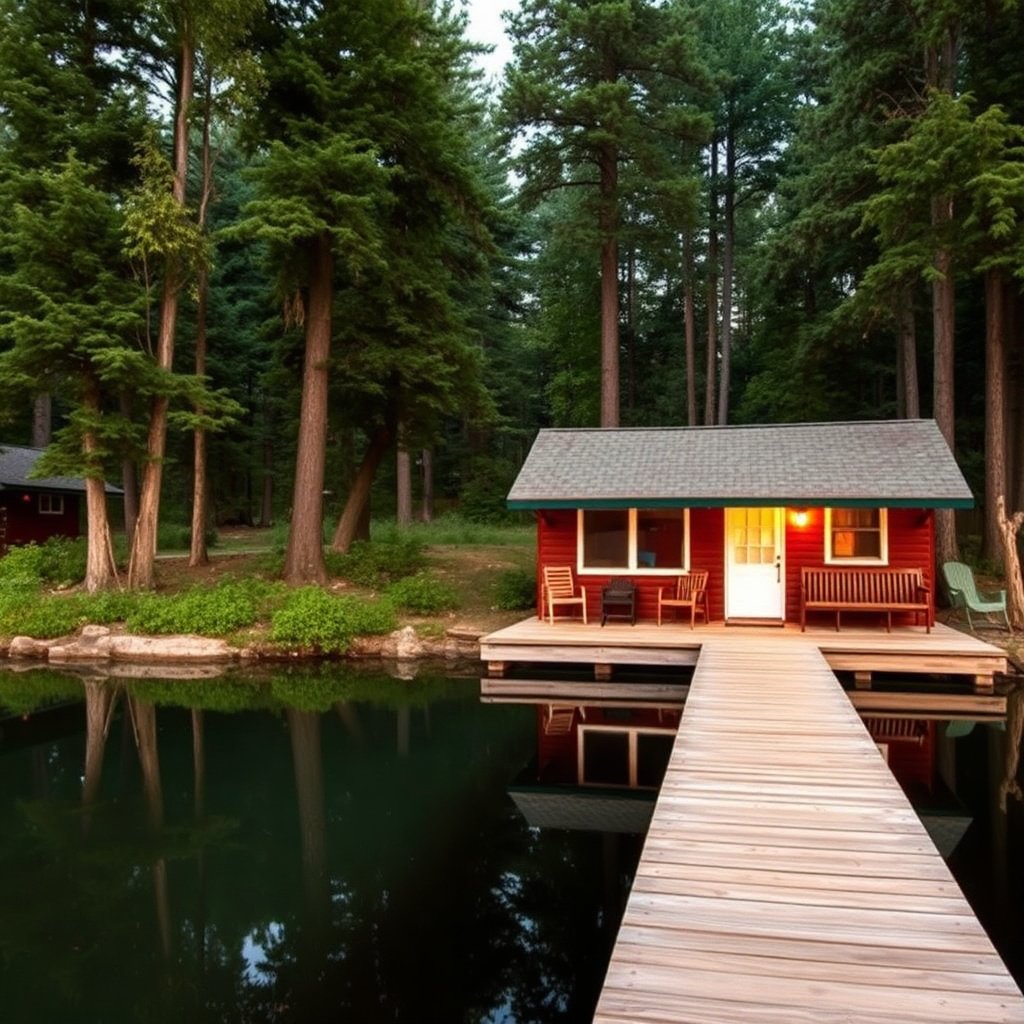
Vacation Homes and Weekend Getaways
Properties used seasonally, such as lake houses or mountain cabins, qualify as second homes if you live somewhere else most of the year. Lenders consider these lower-risk if occupied periodically since they tend to retain value and are less likely to be rented out full-time.
Vacation homes require proof that the property will be used personally, which affects financing terms and regulations.
- Seasonal use is key for classification
- Limited rental use allowed under most loans
Urban Second Homes and Investment Considerations
Urban second homes might include city condos or apartments where you spend part of the year. Lenders carefully assess how the property is used—strictly second homes versus rental or investment properties—as this impacts loan eligibility and rates.
Investment properties face higher interest rates and stricter underwriting than second homes primarily used for personal use.
- Second home status requires personal use
- Rental properties treated differently by lenders
Application Process for a Second Home Mortgage

Document Preparation and Pre-Approval
Start by gathering essential paperwork: proof of income, credit reports, current mortgage statements, and bank statements for reserves. Getting pre-approved gives you a clear sense of what you can afford and strengthens your offer on the second home.
Pre-approval involves a lender reviewing your finances and creditworthiness before you shop, helping set expectations and streamlining the eventual loan approval.
- Collect tax returns, pay stubs, credit reports
- Get pre-approval to understand borrowing power
For more on this, see our related guide: How to Finance a Vacation Home: A Practical Guide for Buyers.
Final Approval and Closing Steps
Once you find a suitable second home, submit a formal loan application with all required documentation. The lender will order an appraisal to verify the property’s value and assess risk.
After underwriting approval, review loan terms carefully before closing. Expect to pay closing costs similar to those on primary home loans, including appraisal fees, title insurance, and lender fees.
- Submit application with property details
- Appraisal and underwriting finalize loan terms
- Prepare for closing costs and signing
Tax Implications and Financial Considerations

Mortgage Interest Deductions for Second Homes
Mortgage interest on second homes is generally tax-deductible if the home is used personally and the loan amount falls within IRS limits. This can help reduce the effective cost of borrowing over time.
Keep thorough records of mortgage payments and consult tax professionals to ensure you maximize deductions and comply with regulations.
- Interest deductible on loans up to $750,000 combined with primary residence
- Personal use required for deductions
For more detailed guidelines on second home mortgage requirements, the Consumer Financial Protection Bureau offers a comprehensive overview. second home mortgage information.
Managing Budget and Ongoing Costs
Beyond the mortgage, factor in property taxes, insurance, utilities, and maintenance for your second home. Budgeting for these expenses is essential to avoid financial surprises.
Consider setting aside an emergency fund specifically for the second home to cover unexpected repairs or vacancy periods if you choose to rent it out occasionally.
- Account for taxes and insurance in budgeting
- Maintain an emergency reserve for upkeep
Second Home Mortgage Options Comparison
Here’s a comparison of common mortgage options for second homes, highlighting key factors like down payment, interest rates, and eligibility.
| Loan Type | Typical Down Payment | Interest Rate Range | Eligibility Notes |
|---|---|---|---|
| Conventional Loan | 10-20% | 3.5%-5% | Requires good credit, personal use only |
| Jumbo Loan | 20%+ | 4%-6% | For high-value properties over conforming limits |
| VA Loan | 0% | 3%-4.5% | For eligible veterans; occupancy rules apply |
| FHA Loan | N/A | N/A | Not available for second homes |
| Adjustable-Rate Mortgage (ARM) | 10-20% | Lower initial rates | Good for short-term ownership |
Frequently Asked Questions
Can I use a second home as a rental property?
Using a second home as a rental property changes its classification to an investment property, which usually requires different loans with higher rates and larger down payments.
Is the down payment for a second home higher than for a primary residence?
Yes, down payments for second homes typically range from 10% to 20%, which is higher than many options for primary residences.
Will a second home mortgage affect my ability to get another loan?
Owning a second home increases your debt obligations, which can impact your debt-to-income ratio and influence approval for future loans.
Can I deduct mortgage interest on a second home for taxes?
Mortgage interest on a second home is usually tax-deductible if the home is used personally and the loan amount meets IRS limits.
Do I need to live in the second home to get a mortgage?
Lenders require that second homes are used for personal use at least part of the year; properties intended solely for rental or investment do not qualify as second homes.
Key Takeaways
- Lenders require stronger financial profiles for second home mortgages than for primary residences.
- Expect larger down payments, typically 10-20%, for second home loans.
- Personal use of the property distinguishes second homes from investment properties in loan terms.
- Thorough preparation and documentation improve approval chances and loan terms.
Conclusion
Securing a mortgage for a second home involves carefully evaluating your financial situation and understanding lender expectations that differ from primary residence loans. Key points include maintaining a strong credit score, a manageable debt-to-income ratio, and proof of stable income. Preparing sufficient reserves and budgeting for additional costs will strengthen your application and ensure you can sustain ownership comfortably over time.
For those considering specific loan options, conventional loans are often the most straightforward choice, especially if your credit and finances are solid. Jumbo loans are necessary for pricier properties, while VA loans serve qualified veterans under specific conditions. Avoid FHA loans for second homes as they are generally not available for this purpose. If you plan short-term use or anticipate selling in a few years, adjustable-rate mortgages (ARMs) can offer attractive initial rates.
The next step is to gather your financial documents and seek pre-approval to clarify your borrowing limit. Engage with multiple lenders to compare offers and terms specific to second home mortgages. With careful planning and an informed approach, you can confidently secure financing for your second home and enjoy the lifestyle benefits it provides.